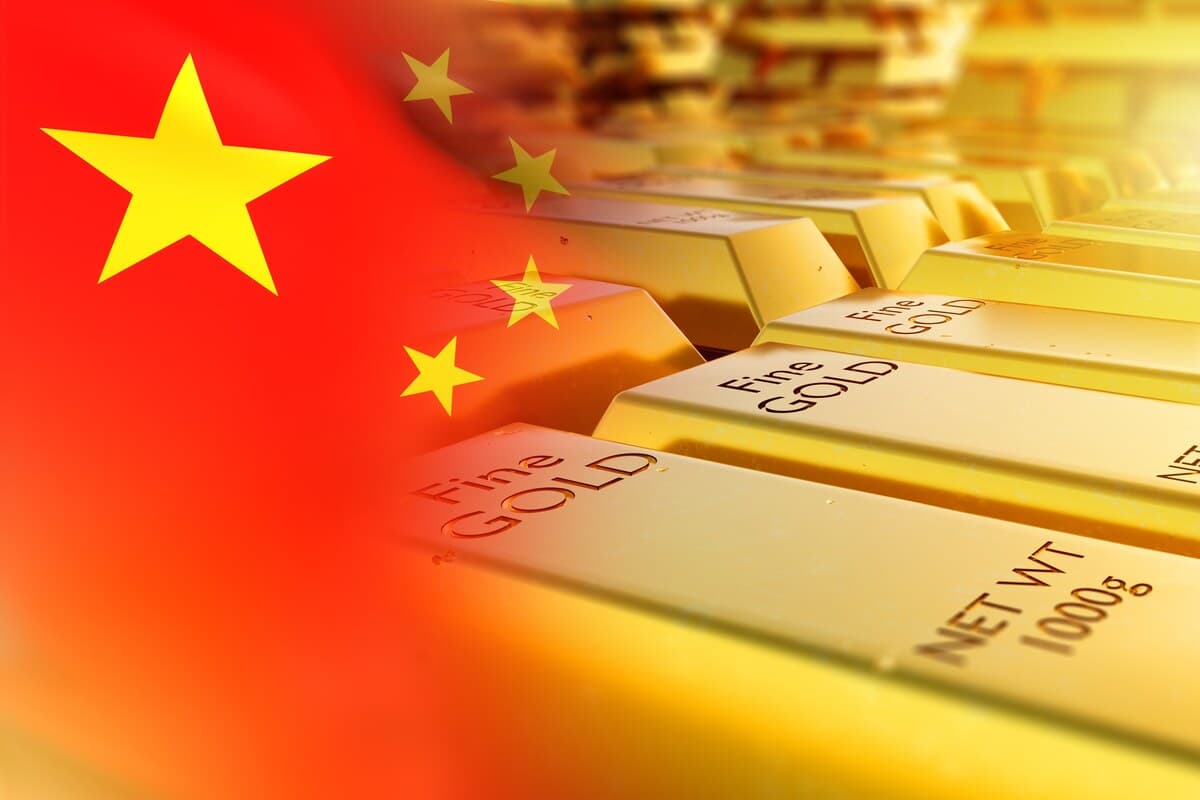
China has spent a record amount importing gold this year, bringing more than 1,000 tonnes of the precious metal into the country during the first eight months of 2026 as elevated prices and strong demand reshape the global bullion market.
The world's second-largest economy spent almost $160 billion on gold imports between January and August, according to trade data reported by the Financial Times. The scale of the purchases reflects both the dramatic increase in the price of gold and sustained appetite for the metal among Chinese investors.
China has long been one of the world's most important gold markets, with demand coming from jewellery buyers, investors and financial institutions. The country is also the world's largest gold producer, but domestic production is insufficient to satisfy its enormous internal demand, making imports an important part of the market.
The latest figures are particularly striking because buyers have continued purchasing gold despite historically high prices. Normally, rapidly rising prices can discourage jewellery consumption and other price-sensitive demand, but concerns about economic conditions and the search for alternative stores of value have continued to support investment interest.
Gold has experienced a remarkable period as investors around the world respond to geopolitical uncertainty, expectations surrounding interest rates, concerns about government debt and attempts to diversify portfolios away from conventional financial assets.
China adds another dimension to that global trend. The country's property sector has historically absorbed large amounts of household wealth, but years of difficulties among property developers and weaker expectations for house-price appreciation have encouraged some investors to look for alternatives.
Gold has emerged as one of those alternatives.
Chinese households have traditionally viewed the precious metal as both jewellery and a store of wealth. Investment products such as gold bars, coins and exchange-traded products have expanded the ways in which individuals can gain exposure to bullion beyond purchasing jewellery.
Institutional demand has also attracted attention. China's central bank has accumulated gold over recent years as part of its reserves, contributing to a broader trend in which central banks around the world have increased their exposure to the metal.
Central-bank buying and consumer demand are not the same thing, however, and China's trade figures capture a broader market than official reserve purchases alone. The import numbers therefore should not be interpreted as meaning that China's central bank purchased all of the gold entering the country.
The extraordinary dollar value of this year's imports is also partly explained by the price itself. When gold becomes substantially more expensive, importing the same physical quantity requires far more money. The nearly $160 billion figure consequently reflects a combination of large physical demand and elevated bullion prices.
China's influence matters well beyond its borders because of the sheer size of its market. Strong Chinese demand can tighten the availability of physical bullion internationally and contribute to premiums between prices in China and major global trading centres.
Gold enters mainland China through regulated channels, with authorities exercising significant control over imports. Changes in import quotas, domestic demand and price differences between Chinese and international markets can therefore affect how much metal flows into the country at different points in the year.
The surge also comes during a broader global reassessment of gold's role in investment portfolios. Unlike shares or bonds, gold does not generate dividends or interest. Investors generally hold it because of its scarcity, liquidity and historical role as a store of value, particularly during periods of uncertainty.
That does not mean rising gold prices are guaranteed to continue. Bullion prices can fall sharply, and demand can weaken if interest rates, currency movements, investor sentiment or economic conditions change.
For China, however, the first eight months of 2026 have demonstrated the extraordinary amount of capital that investors are currently willing to direct towards the precious metal.
Importing more than 1,000 tonnes in eight months is significant on its own. Spending almost $160 billion to do so illustrates how the combination of enormous Chinese demand and historically expensive bullion has turned the country's gold trade into one of the biggest stories in global commodities this year.