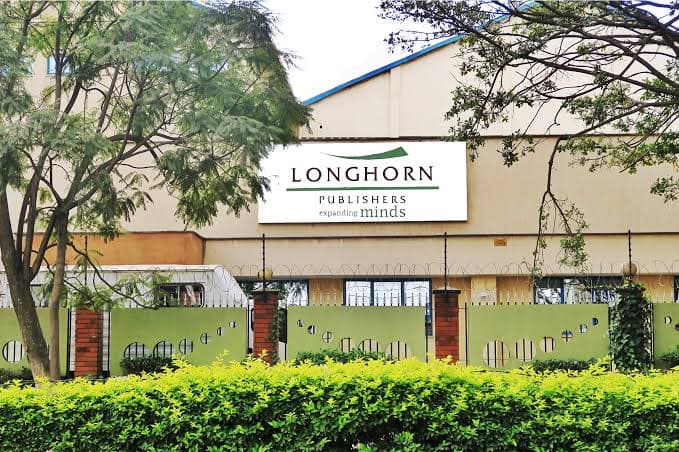
Kenyan education publisher Longhorn Publishers has recorded a historic net loss of Sh949.6 million for the financial year ended June 2026, highlighting the financial consequences of the country's transition from the 8-4-4 education system to the Competency-Based Curriculum (CBC).
The loss represents the company's worst annual financial performance since listing on the Nairobi Securities Exchange in 2012. It is also nearly four times the Sh261.4 million loss reported in the previous financial year.
The sharp deterioration was largely driven by the company's decision to recognise a Sh518 million impairment charge on investments associated with textbooks developed for the outgoing 8-4-4 curriculum.
The charge reflects the declining commercial value of educational materials designed for a system that is progressively being replaced by the new curriculum.
Longhorn Managing Director Simon Ngigi explained that the approval of Grade 12 CBC textbooks approximately two months ago marked an important turning point for the publishing industry.
The approval effectively confirmed the final stage of the transition away from the previous curriculum, prompting Longhorn to make full provisions for its remaining investments in 8-4-4 learning materials.
However, the impairment does not mean that every textbook covered by the provision has immediately become unsaleable.
Students in Form Three and Form Four are still expected to complete their studies under the outgoing system before the transition reaches those classes in 2027 and 2028, respectively.
This means that some demand for 8-4-4 textbooks could continue during the remaining transition period. Longhorn expects to sell portions of its existing inventory over the next year, potentially recovering some value from materials already affected by the accounting provisions.
The financial impact of the curriculum transition was compounded by the removal of previously recognised deferred tax assets worth Sh262 million.
Together, these accounting adjustments significantly affected the company's reported results, despite improvements in its underlying sales performance.
Longhorn's revenue increased by 21 per cent to Sh811 million from Sh672.1 million in the previous financial year. The growth was supported by wider market coverage and improved sales of its educational products.
However, the impairment charges contributed to a sharp increase in the reported cost of sales, which rose by 75.4 per cent to Sh913.8 million.
The company indicated that, excluding the curriculum-related impairment charges, it would have recorded an operating profit of approximately Sh16 million. This would have represented an improvement from the Sh20 million operating loss reported in the preceding year.
The distinction is important because it shows that the company's record loss was not caused solely by declining demand for its products.
Instead, a significant portion resulted from accounting adjustments reflecting the reduced value of investments associated with the discontinued education system.
Nevertheless, Longhorn continues facing operational challenges, including delayed institutional textbook purchases and constrained funding within its key markets.
These difficulties have affected the timing of orders and the company's ability to generate consistent revenue from educational institutions.
The financial pressure has also weakened Longhorn's balance sheet.
Total assets declined by 40.2 per cent to Sh1.33 billion, while shareholders' equity fell from a positive Sh18.1 million to a negative Sh1.03 billion.
Negative shareholders' equity means that the company's reported liabilities exceed its assets, creating additional pressure to strengthen its financial position and rebuild investor confidence.
Longhorn's difficulties illustrate the wider challenges facing Kenya's educational publishing industry as schools transition to new learning frameworks.
Publishers traditionally invest substantial resources in developing textbooks, obtaining curriculum approvals, printing materials and distributing them to educational institutions.
When a national curriculum changes, previously developed books can lose commercial value before publishers have fully recovered their investments.
The transition to CBC has therefore required publishing companies to revise their product portfolios, develop new learning materials and adjust to changing procurement requirements.
Despite its financial difficulties, Longhorn believes the completion of major curriculum revisions could provide a foundation for future growth.
The company is investing in CBC-aligned educational content and expanding its digital learning offerings through the LoHo Learning platform.
It is also pursuing product diversification, improved operational efficiency and opportunities to generate more consistent revenue from different customer segments.
Digital learning represents a potential growth opportunity as schools increasingly adopt technology-supported teaching and learning resources.
However, the company's recovery will depend on its ability to convert these investments into sustainable sales, improve cash generation and manage its financial obligations.
Longhorn's record Sh949.6 million loss demonstrates the substantial financial impact that education reforms can have on businesses supplying learning materials. While the transition from 8-4-4 to CBC has created immediate challenges, the publisher is now positioning its future around curriculum-aligned content, digital learning and a more diversified education business.